National Housing Market Trends: 2% Decline Predicted for Q3 2026
A recent report projects a 2% decline in U.S. home sales for Q3 2026, reflecting evolving economic conditions and shifts in buyer behavior impacting national housing market trends.
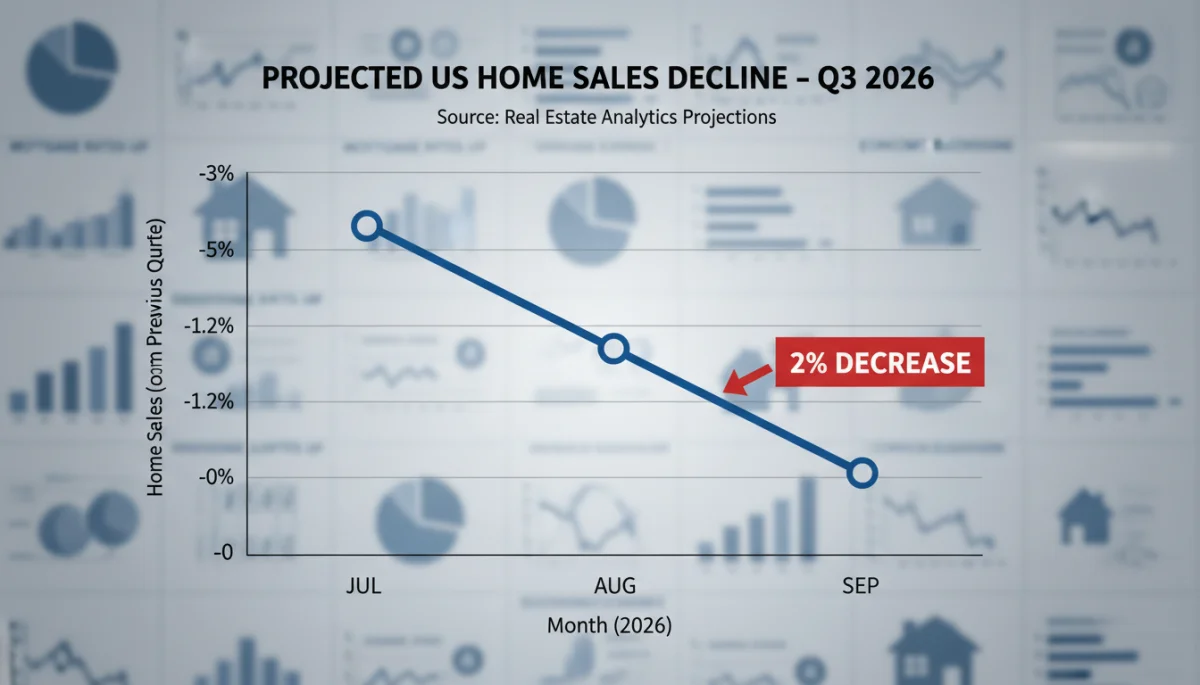
The latest report on national housing market trends reveals a significant forecast: a 2% decline in home sales is predicted for Q3 2026. This projection signals a pivotal moment for homebuyers, sellers, and investors across the United States, urging a closer look at the underlying factors shaping the future of real estate.
Understanding the Q3 2026 Forecast
The prediction of a 2% decline in home sales for Q3 2026 is not an isolated event but rather a culmination of various economic and market-specific forces. This forecast, derived from comprehensive analyses, indicates a cooling period following several years of dynamic activity in the U.S. housing sector. Understanding these dynamics is crucial for anyone involved in the real estate market.
Several key indicators contribute to this outlook. Interest rate adjustments by the Federal Reserve, evolving consumer confidence, and shifts in housing inventory all play significant roles. These elements collectively paint a picture of a market entering a new phase, moving away from the rapid appreciation seen in previous years towards a more measured pace.
Economic Indicators Influencing the Decline
The economic landscape is a primary driver of housing market performance. Current inflation rates, employment figures, and broader GDP growth directly impact affordability and buyer sentiment. When these indicators signal uncertainty, potential buyers often delay large investments like home purchases.
- Interest Rate Hikes: Rising mortgage rates directly affect purchasing power, making monthly payments higher for the same loan amount.
- Inflationary Pressures: Increased costs of living reduce disposable income, further impacting housing affordability.
- Job Market Stability: While generally robust, any signs of cooling in the job market can dampen consumer confidence.
These factors combine to create a challenging environment for sustained growth in home sales. The projected decline suggests that the market is adjusting to these new economic realities, with buyers becoming more cautious and selective.
Moreover, the supply side of the equation also plays a role. While new construction has seen some recovery, it has often struggled to keep pace with demand in many areas, leading to price volatility. However, a slight increase in existing home inventory combined with reduced demand could contribute to the predicted sales dip.
Factors Driving the Predicted Decline
Unpacking the specific factors behind the anticipated 2% decline in home sales for Q3 2026 reveals a complex interplay of monetary policy, supply-demand dynamics, and demographic shifts. This section delves into these critical elements, providing a clearer understanding of the forces at play in the national housing market trends.
Forecasters point to several interconnected reasons for this expected downturn. High interest rates, persistent inflation, and a subtle but significant shift in buyer sentiment are among the most prominent. These elements are creating a challenging environment for both buyers and sellers, leading to a more cautious market.
Mortgage Rates and Affordability Challenges
The Federal Reserve’s stance on monetary policy, particularly its decisions regarding the federal funds rate, has a direct and profound impact on mortgage rates. As borrowing costs increase, the overall affordability of homes decreases, even if listing prices remain stable. This phenomenon disproportionately affects first-time homebuyers and those with tighter budgets.
- Increased Monthly Payments: Higher rates translate to larger monthly mortgage payments, reducing the pool of eligible buyers.
- Reduced Purchasing Power: Buyers qualify for smaller loan amounts, forcing them to look at less expensive homes or delay purchases.
- Impact on Market Velocity: Slower sales cycles as buyers take more time to commit, or withdraw from the market altogether.
The continuous adjustment of mortgage rates in response to broader economic conditions is a critical component of the predicted sales decline. This makes financial planning more complex for prospective homeowners.
Furthermore, while home prices have seen some stabilization, the cumulative effect of higher prices combined with elevated interest rates creates a significant hurdle for many. This affordability crunch is a major contributor to the expected slowdown.
Regional Variations and Their Impact
While the national housing market trends suggest an overall 2% decline in home sales for Q3 2026, it is imperative to recognize that the impact will not be uniform across all regions of the United States. Local economic conditions, population shifts, and housing inventory levels will create significant variations in how this prediction manifests.
Some areas, particularly those that experienced rapid appreciation and intense bidding wars in recent years, may see a more pronounced cooling. Conversely, regions with strong job growth, diverse economies, and more balanced housing supply might experience milder adjustments or even continued, albeit slower, growth.
Hotspots and Coldspots: A Geographic Breakdown
Certain metropolitan areas and states are more susceptible to market fluctuations due to their unique characteristics. For example, tech-heavy markets that saw an influx of remote workers might experience a rebalancing, while traditional industrial hubs could see more stable, if modest, activity.
- Coastal Metros: Often characterized by high prices and limited inventory, these areas might see price corrections or significant drops in sales volume due to affordability constraints.
- Sun Belt States: Regions that experienced massive population growth might still maintain relatively strong demand, but the pace of sales could moderate.
- Midwest and Rural Areas: These markets often exhibit greater stability, with less extreme price swings, making them potentially more resilient to national downturns.
Understanding these regional nuances is vital for anyone making real estate decisions. What might be a challenging market nationally could present unique opportunities or require different strategies at the local level.
Local employment rates, the presence of major employers, and even local government policies regarding housing development can all influence how a particular area weathers broader market shifts. Therefore, a granular approach to market analysis is always recommended.
Impact on Buyers and Sellers
The predicted 2% decline in home sales for Q3 2026 will undoubtedly reshape the landscape for both prospective buyers and current sellers. Each group will face distinct challenges and opportunities as the market adjusts to new economic realities and shifts in demand. Adapting strategies will be key to navigating these evolving national housing market trends successfully.
For buyers, a cooling market could mean less competition, more negotiation power, and potentially a slight increase in available inventory. However, higher interest rates will continue to challenge affordability. For sellers, the days of multiple offers above asking price may become less common, requiring a more strategic approach to pricing and marketing.
Strategies for Prospective Buyers
In a market with declining sales, buyers may find themselves in a more favorable position than in recent years. Less frantic competition can allow for more thoughtful decision-making and potentially better terms.
- Patience is Key: With less pressure, buyers can afford to wait for the right property at the right price, rather than rushing into decisions.
- Focus on Affordability: Prioritize homes that fit comfortably within your budget, especially considering higher mortgage rates. Explore different loan products.
- Negotiation Opportunities: Be prepared to negotiate on price, contingencies, and even seller concessions, as sellers may be more flexible.
Thorough due diligence, including professional home inspections and understanding local market conditions, becomes even more important. Buyers should also secure pre-approval for mortgages to demonstrate their seriousness and financial readiness.
This period could also be an opportune time for buyers who were previously priced out of the market to re-enter, especially if inventory begins to expand in their desired locations.
The Role of Inventory and Supply
The balance between housing inventory and buyer demand is a fundamental driver of market health. The predicted 2% decline in home sales for Q3 2026 is intricately linked to shifts in both these factors, particularly the availability of homes on the market. Understanding the role of inventory is crucial for comprehending the broader national housing market trends.
For several years, many markets have struggled with chronically low inventory, contributing to rapid price appreciation. However, as sales slow, inventory levels may begin to stabilize or even increase in certain areas, providing more options for buyers and potentially easing price pressures.
Current Inventory Levels and Future Projections
The supply side of the housing market is influenced by new construction rates, homeowner decisions to sell, and the pace at which homes are purchased. A slowdown in sales, even a modest one, can lead to inventory accumulating if new listings continue at a steady pace.
- Existing Home Sales: A decline here means homes stay on the market longer, increasing overall inventory.
- New Construction: While still facing challenges, an increase in new builds can gradually alleviate supply shortages in some regions.
- Homeowner Reluctance: Some homeowners with low mortgage rates may be hesitant to sell, limiting new listings in certain price points.
A more balanced inventory-to-demand ratio could lead to a less frenzied market, benefiting buyers with more choices and less pressure to overbid. This shift could also encourage sellers to price their homes more competitively.
However, it’s important to note that a 2% decline in sales does not necessarily equate to a massive oversupply. The market is more likely to move towards a state of equilibrium, rather than a significant glut of homes, depending on regional dynamics and economic resilience.
Expert Forecasts and Long-Term Outlook
While the immediate forecast points to a 2% decline in home sales for Q3 2026, understanding the broader expert consensus and long-term outlook is essential for a comprehensive view of national housing market trends. Real estate analysts and economists are carefully weighing various indicators to project where the market might head beyond this immediate downturn.
Most experts agree that the market is undergoing a necessary correction and normalization phase after an unprecedented period of growth. The long-term outlook suggests a more stable, albeit slower, appreciation, with affordability remaining a key concern for many years to come. This period of adjustment is seen as a healthy development for market sustainability.
What Analysts Are Saying
Economists are closely monitoring inflation rates, Federal Reserve policies, and employment data to refine their long-term predictions. The consensus leans towards a market that, while cooling, is unlikely to crash dramatically, given underlying demand and demographic shifts.
- Gradual Stabilization: Expect a period of slower price growth, moving towards more sustainable appreciation rates.
- Continued Demand: Demographic factors, such as millennials entering prime homebuying age, will sustain underlying demand.
- Interest Rate Volatility: Mortgage rates are expected to remain sensitive to economic data, influencing buyer behavior.
The long-term health of the housing market will largely depend on the overall economic stability of the United States. Factors like wage growth, controlled inflation, and continued job creation will be crucial in ensuring that housing remains accessible and a sound investment.
Despite the short-term predicted decline, real estate remains a fundamental asset for many Americans. Strategic planning, informed decision-making, and an understanding of local market nuances will be paramount for successful navigation in the coming years.
| Key Aspect | Description |
|---|---|
| Sales Forecast | 2% decline in U.S. home sales predicted for Q3 2026. |
| Key Drivers | Rising interest rates, persistent inflation, and shifting buyer sentiment. |
| Regional Impact | Varied effects, with some metros seeing larger adjustments than others. |
| Market Outlook | Correction phase towards a more stable and sustainable housing market. |
Frequently Asked Questions About Housing Market Trends
For the average homeowner, a 2% decline in home sales indicates a cooling market. This typically means homes might stay on the market longer, and sellers may need to be more flexible on pricing or negotiations compared to recent years of rapid sales.
While a sales decline often precedes price adjustments, a 2% drop in sales doesn’t automatically mean a significant price crash. Prices might stabilize or see modest corrections in some areas, especially those that experienced rapid appreciation, rather than widespread steep declines.
Rising interest rates directly impact affordability by increasing monthly mortgage payments. This reduces purchasing power, meaning homebuyers might qualify for smaller loans or face higher costs, making them more cautious and selective in their home search.
Regions that experienced significant price surges and high competition in recent years, such as some coastal metros or popular growth areas, might see a more pronounced impact. Conversely, markets with strong economic fundamentals and balanced supply may experience milder effects.
Sellers should focus on competitive pricing, professional staging, and effective marketing. Being realistic about market value and prepared for longer listing periods and potential negotiations will be crucial for a successful sale in a cooling market environment.
Conclusion
The forecast of a 2% decline in U.S. home sales for Q3 2026 marks a significant inflection point in the national housing market trends. This anticipated adjustment, driven by evolving economic conditions, interest rate policies, and shifts in inventory, signals a transition from a seller-dominated market to one seeking greater equilibrium. While challenges like affordability persist, this period also presents unique opportunities for informed buyers and sellers to navigate the market strategically. Understanding regional nuances and expert insights will be paramount in making sound real estate decisions as the market continues its path toward normalization and sustainable growth.
